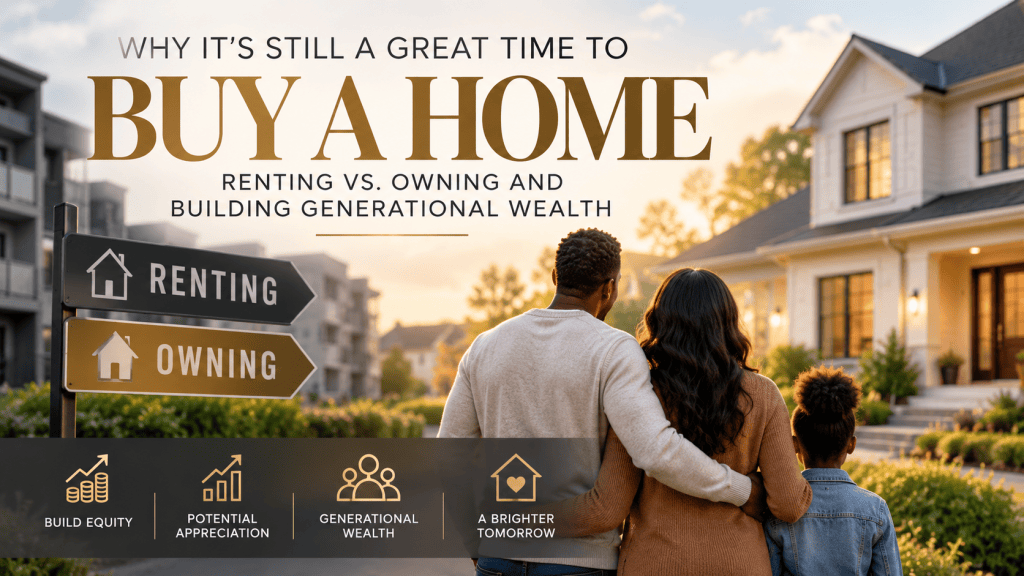
With conversations about interest rates, home prices and affordability everywhere, it’s understandable that some potential buyers are wondering whether they should purchase a home now or continue renting.
But there’s another question worth asking:
If you are financially prepared to buy a home, what could waiting cost you?
There will probably never be a “perfect” housing market. Rates change. Home prices change. Inventory changes. What matters most is whether buying makes sense for your finances, your lifestyle and your long-term goals.
For many people who are financially ready, homeownership can offer something renting cannot: the opportunity to build equity and own an asset that may contribute to long-term and generational wealth.
You’re Paying for Housing Either Way
Unless you are living somewhere rent-free, housing is already part of your monthly budget.
When you rent, your payment gives you the right to live in someone else’s property for the agreed-upon period. Renting can make sense, especially when you need flexibility, aren’t financially prepared for the responsibilities of homeownership or don’t plan to remain in an area long-term.
But your monthly rent does not give you ownership in the property.
With a mortgage, a portion of your payment generally goes toward paying down the principal balance of your loan. Over time, that can help increase your ownership stake in the property.
That is one of the fundamental differences between renting and owning.
Renting vs. Owning: Look Beyond the Monthly Payment
It’s easy to compare a rent payment with a potential mortgage payment and stop there. But there is more to consider.
Renters typically have fewer responsibilities for major repairs and greater flexibility to move. However, they generally have little control over future rent increases and do not benefit financially if the property increases in value.
Homeowners take on additional expenses and responsibilities, including maintenance, repairs, property taxes and homeowners insurance. But they also have the opportunity to build equity, potentially benefit from appreciation and have greater control over their property.
Buying isn’t automatically the better choice in every situation.
But when you are financially prepared and plan to stay in the home long enough, homeownership can become much more than a monthly housing expense.
Your Home Can Become Part of Your Wealth-Building Strategy
One of the biggest reasons I believe in educating people about homeownership is equity.
Equity is essentially the difference between what your home is worth and what you still owe on it.
As you pay down your mortgage principal, your equity can increase. If the property appreciates over time, that can potentially increase your equity as well.
For example, imagine purchasing a home and living there for many years. During that time, you are gradually paying down your mortgage. If the home’s value also rises, you may eventually have a significant asset instead of simply having a history of monthly housing payments.
Of course, appreciation is never guaranteed, and real estate values can rise or fall. That’s why purchasing a home should be viewed as a long-term financial decision rather than a promise of quick wealth.
Homeownership and Generational Wealth
This is where the conversation becomes bigger than simply buying a house.
What are you building that can potentially benefit the generation coming behind you?
A home can become an asset that may be passed down to your children or other heirs. It may eventually be sold, with the proceeds becoming part of an inheritance. Depending on a homeowner’s circumstances, equity may also play a role in future financial or investment decisions.
That doesn’t mean purchasing one house automatically creates generational wealth. Building wealth usually requires planning, maintaining the property, managing debt responsibly and making thoughtful financial and estate-planning decisions.
But homeownership can be one piece of that foundation.
Instead of thinking only about where you’re going to live today, consider what you may be able to build over the next 10, 20 or 30 years.
Stop Waiting for the “Perfect” Market
One of the most common things I hear is some version of:
“I’m waiting for interest rates to come down.”
Interest rates absolutely matter because they affect your monthly payment and overall borrowing costs. But rates are only one part of determining whether you are ready to purchase.
Your income, credit, existing debt, savings, loan program, down payment, closing costs, available assistance, monthly budget and future plans all matter.
Instead of asking:
“Is this the perfect time to buy?”
Consider asking:
“Am I financially prepared to buy, and does buying make sense for me right now?”
Those are two very different questions.
You May Have More Options Than You Realize
Another reason not to automatically count yourself out of homeownership is that you may not know what programs or financing options are available to you.
Depending on your qualifications and location, there may be loan programs, down-payment assistance, closing-cost assistance or builder incentives that can reduce some of the upfront costs associated with purchasing a home.
You won’t know what you qualify for until you start asking questions.
And starting the conversation doesn’t mean you have to buy a house tomorrow.
Maybe you’re ready now. Maybe you need six months. Maybe you need a year.
Knowing where you stand gives you the opportunity to create a plan.
Homeownership Starts With a Conversation
I believe homeownership should be approached with education, preparation and realistic expectations.
Buying a home isn’t the right move simply because someone tells you that renting is “throwing money away.” Renting can serve an important purpose during different seasons of life.
But if you have the financial ability to purchase, plan to remain in the home long enough and want to begin building an asset of your own, it may be worth exploring homeownership rather than automatically assuming you should wait.
Your first home doesn’t have to be your forever home.
It can simply be your first step toward ownership, equity and potentially building something your family can benefit from for generations.
Are You Ready to Find Out What’s Possible?
You don’t have to figure out the homebuying process alone.
If you’re thinking about purchasing a home, let’s look at your goals, discuss your options and determine what your next step should be.



Leave a comment